Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is an authorised Financial Services Provider (FSP 46449) under the Financial Advisory and Intermediary Services Act (37 of 2002)
September 15, 2026

South African Gold and Foreign Exchange Reserves for August 2026
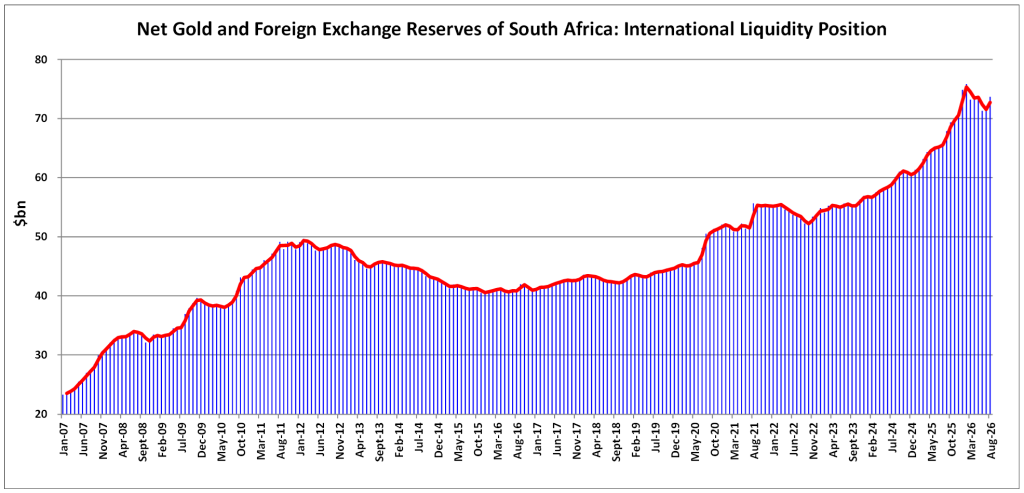
South Africa’s international liquidity position strengthened in August 2026, with net gold and foreign exchange reserves rising by USD 1,9 billion as the rand gained nearly 30c against the US dollar and the gold price climbed to USD 4 460/oz, some 30% higher than a year earlier. Yet beneath these encouraging headline figures lies a far more complex picture: the ongoing conflict in the Middle East and tensions around the Strait of Hormuz are keeping oil prices elevated, while shifting US tariff measures, a one-year AGOA extension and the Federal Reserve’s decision to hold rates steady all point to continued volatility for the rand. With the South African Reserve Bank’s third-quarter interest rate decisions hanging in the balance, this report unpacks what these commodity and currency movements mean for inflation, the mining sector and South Africa’s economic outlook for the remainder of the year.

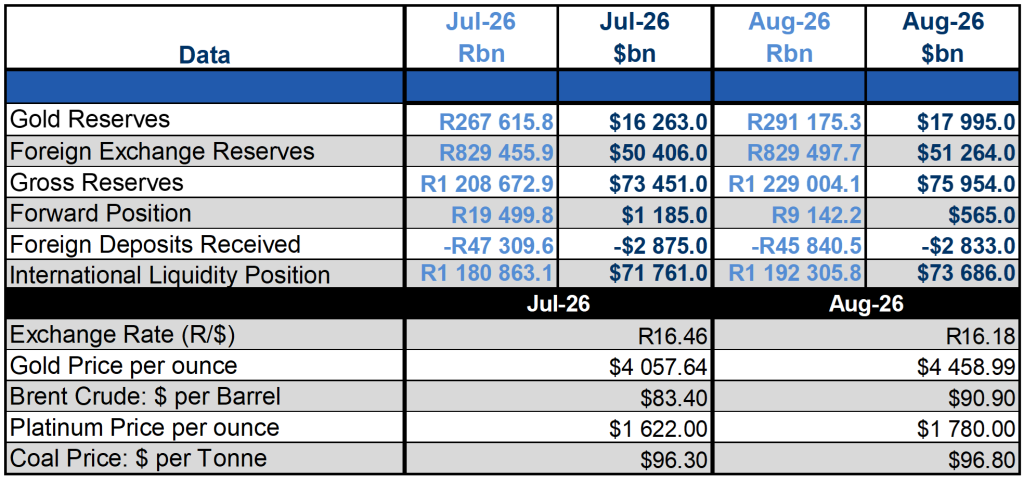
South Africa’s international liquidity position, measured by net gold and foreign exchange reserves, improved in both US dollar and rand terms in August 2026. According to the South African Reserve Bank (SARB), the rand strengthened by nearly 30c against the US dollar between July and August, despite the ongoing conflict in the Middle East.

Reserves rose by USD 1,9 billion in August, following an increase of USD 423 million in July 2026.

Gold continues to support reserves

The gold price remains elevated. It rose by just over USD 400/oz during August, from USD 4 057/oz in July to USD 4 460/oz, and is still around 30% higher than a year earlier. This sustained strength in the gold price has been a key factor supporting South Africa’s reserves from January through August, against the backdrop of the conflict in the Middle East.

In US dollar terms, foreign reserves increased in August compared with the previous month. The SARB also purchased US dollars in open market operations, partly in response to a slightly stronger rand and a slightly weaker dollar, which influenced the country’s net international liquidity position at the time.

Why commodity trends matter

Key commodities such as gold, oil, platinum and coal provide valuable insight into the health of South Africa’s mining sector and the inflation outlook. Monitoring these trends is essential for assessing inflation prospects, particularly given ongoing international developments and potential trade restrictions with the United States following the tariff measures introduced in August.

Implications for interest rates and the rand

Inflation expectations will shape the SARB’s interest rate decisions in the third quarter of 2026, especially amid the Middle East conflict and tensions around the Strait of Hormuz. While the rand has been relatively stable and slightly stronger of late, oil prices remain higher than at the start of 2026, which adds to inflationary pressure.

Several external factors could also increase market volatility:

  • Continued global geopolitical tensions
  • Possible changes to trade agreements, including the African Growth and Opportunity Act (AGOA), which the US administration has extended by one year
  • The reduction of the 30% reciprocal tariffs to 12,5% for now, after the US Supreme Court ruled that the 30% tariffs were unconstitutional and had to be withdrawn
  • The US Federal Reserve’s decision to keep interest rates unchanged at its announcement on 29 July 2026

Given these developments, the rand may continue to experience short-term fluctuations despite its recent appreciation against the US dollar. This could influence South Africa’s economic outlook for the remainder of the year.


More Coverage

South Africa’s August 2026 inflation data present a complex outlook: headline CPI rose to 4.4%, remaining below market expectations yet above the upper limit of the inflation target range, while services inflation continued to climb, and fuel and transport costs exerted further pressure on households and businesses. With the economy contracting, international oil prices rising and global uncertainties, including Middle East tensions and tariff disputes, continuing to weigh on the rand and domestic prices, attention is now focused on the South African Reserve Bank’s next interest-rate decision. Read the full report for an analysis of the factors driving inflation, the risks facing the economy and what the latest developments could mean for consumers, businesses and monetary policy in the months ahead.
The recent Electoral Court ruling dismissing the ANC’s bid to compel the IEC to accept late candidate submissions is a significant event with profound implications for the upcoming 4 November 2026 local government elections.
South Africa’s retail sector delivered a striking surprise in July 2026, with sales climbing 3.4% against market expectations of a 3.0% contraction, but the story beneath that headline number is far more nuanced than it first appears. This report unpacks the fragile balancing act facing local households: inflation easing to 4.3% yet still stubbornly above the SARB’s new 2–4% target band, administered prices and utility costs rising by more than 4.0%, wage growth lagging behind severe fuel shocks, and the lingering effect of May’s 25-basis-point rate hike prompted by inflationary pressures well beyond Pretoria’s control. We examine why business confidence firmed (SACCI up from 123.5 to 125.4) while consumer sentiment slumped sharply (FNB/BER down from -7 to -19), which categories, from “other retailers” to general dealers and household goods, actually carried the growth, and what the extension of AGOA to end-2027 means now that fresh visa tensions between Washington and Pretoria have placed South Africa’s eligibility squarely under the microscope. Read the full report to understand whether this recovery has the legs to survive higher fuel prices, a possible second rate increase, and a second-quarter contraction in economic activity — or whether July’s good news was simply borrowed from the easing cycle of 2024/25.
South Africa’s business profitability showed surprising resilience in the second quarter of 2026, outpacing inflation despite a 0.2% contraction in economic activity, higher oil and import prices, trade tariffs, and ongoing diplomatic tensions. While overall profit growth slowed from the first quarter, several sectors, including transport and logistics, mining, electricity and utilities, personal services, and trade, recorded substantial gains, offering important clues about where the economy’s strongest opportunities may lie. This report examines the forces shaping Gross Operating Surplus across key industries, explains the mounting pressures on company performance, and considers whether easing geopolitical tensions, lower oil prices, and greater policy certainty could unlock stronger economic activity, employment, and investment in the months and years ahead.
South Africa’s international liquidity position strengthened in August 2026, with net gold and foreign exchange reserves rising by USD 1,9 billion as the rand gained nearly 30c against the US dollar and the gold price climbed to USD 4 460/oz, some 30% higher than a year earlier. Yet beneath these encouraging headline figures lies a far more complex picture: the ongoing conflict in the Middle East and tensions around the Strait of Hormuz are keeping oil prices elevated, while shifting US tariff measures, a one-year AGOA extension and the Federal Reserve’s decision to hold rates steady all point to continued volatility for the rand. With the South African Reserve Bank’s third-quarter interest rate decisions hanging in the balance, this report unpacks what these commodity and currency movements mean for inflation, the mining sector and South Africa’s economic outlook for the remainder of the year.