Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is an authorised Financial Services Provider (FSP 46449) under the Financial Advisory and Intermediary Services Act (37 of 2002)
September 15, 2026

Mining Production and Sales for July 2026
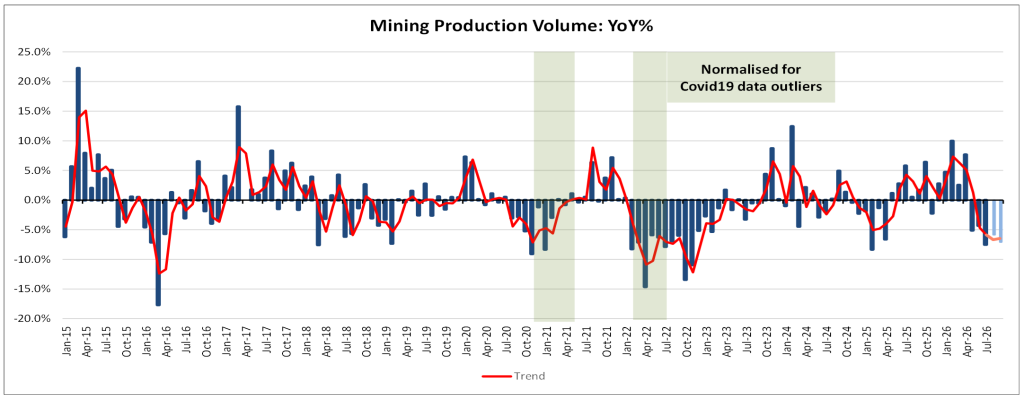
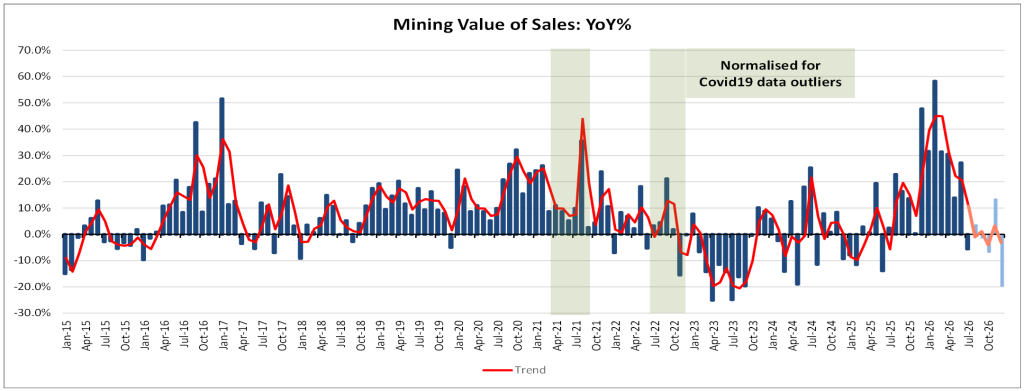
South Africa’s mining sector is facing mounting pressure, with production falling 7.5% in July 2026 after a revised 4.3% decline in June, while the rolling three-month contraction reached 5.5% and nominal mining sales dropped 5.6%. Sharp declines in iron ore, coal, PGMs, gold, manganese, and nickel highlight the sector’s vulnerability, compounded by job losses, rising fuel and energy costs, policy uncertainty, property rights concerns, and growing trade barriers. Yet mining remains indispensable to the economy, supporting approximately 450,000 jobs, generating foreign exchange and contributing to growth. With elevated gold prices and temporary tariff exemptions offering limited relief, this report examines the forces reshaping South Africa’s mining industry—and whether these bright spots can withstand the sector’s deepening structural and geopolitical challenges.

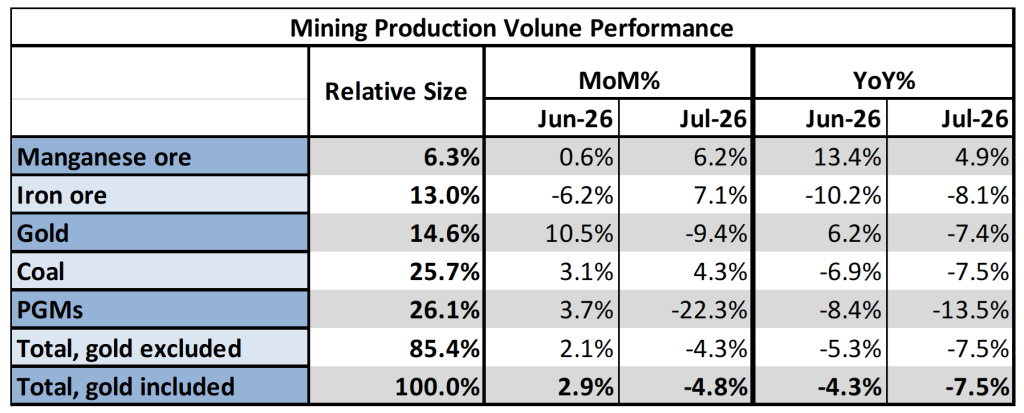
In July 2026, South Africa’s mining activity contracted by 7.5% following the revised 4.3% decrease recorded in June 2026. This contraction was predominantly driven by:

  • An 8.1% decrease in Iron ore mining production, which contributed -1.3 percentage points to the overall mining output for the month.
  • Coal production decreased by 7.5%% during July, while it subtracted 2.0 percentage points from mining production growth
  • An 8.1% contraction in PGM production, which stripped an additional 1.3 percentage points from total mining output growth for the month.

For the rolling quarter ending July 2026, compared with the rolling quarter ending April 2026, seasonally adjusted mining output decreased by 5.5%. This decrease was primarily due to:

  • A 6.7% decrease in manganese mining, which decreased total mining production by 0.5 percentage points,
  • A decrease in mining of PGMs, which contracted by 14.3% and subtracted 4.2 percentage points for the quarter under review,
  • Gold mining, which declined by 4.6% and subtracted an additional 0.4 percentage points from mining output for the quarter and,
  • A decrease in Iron ore mining, which contracted by 2.7% and subtracted 0.4 percentage points for the rolling quarter.

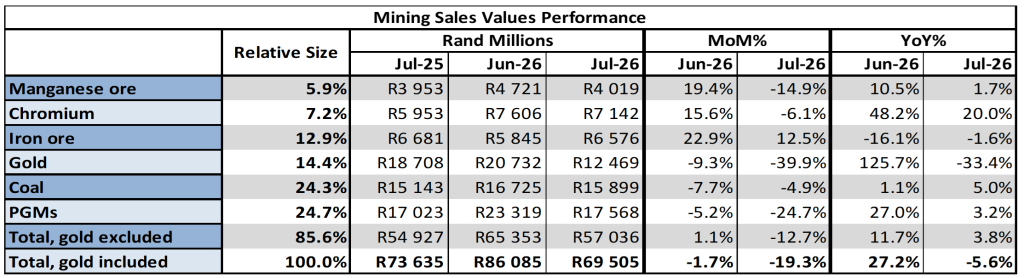
In July, nominal mining sales decreased by 5.6%. This contraction was notably driven by:

  • A decline of 26.0% in ‘other’ non-metallic minerals, which subtracted 0.7 percentage points from overall mining sales growth.
  • A contraction of 33.4% in gold sales, reducing total mining sales by 8.5 percentage points and
  • Nickel sales, which declined by 51.7% and subtracted another 0.4 percentage points from overall mining sales growth for July 2026.

The Mining Sector: Still Vital, But Under Pressure

The mining sector remains a cornerstone of South Africa’s economy, earning valuable foreign exchange and employing approximately 450 000 people. However, this figure represents a decline of around 26 000 jobs from the previous quarter, according to Stats SA’s labour statistics for the second quarter of 2026.

The latest GDP data paints a similar picture. Mining output contracted by 0,7% year on year and by 3,0% quarter on quarter in the second quarter of 2026. This contraction was not unexpected, given the job losses reported in the Quarterly Labour Force Survey, which showed that nearly 30 000 employment opportunities were lost over the period.

Rising costs and policy uncertainty

The ongoing conflict in the Middle East has pushed international oil prices higher, and the effects are now being felt in South Africa’s mining sector through rising energy and fuel costs. These cost pressures, combined with policy uncertainty, concerns over property rights and the latest BEE requirements under the Employment Equity Regulations, 2025, create a difficult operating environment. Together, they discourage mining houses from investing in existing operations, funding exploration or establishing new mines in South Africa.

Some relief from gold prices

On the positive side, the same geopolitical tensions have driven investors towards safe-haven assets such as gold, keeping gold prices relatively high for now. This helps to offset some of the cost increases the sector is currently facing. The sector’s importance to the economy cannot be overstated, given the number of people it employs directly and through related businesses, as well as its role in earning foreign reserves.

Trade challenges persist

Nonetheless, several challenges remain. These include:

  • Concerns over exports to the United States following new tariff measures introduced on 7 August
  • Proposed export tariffs on manganese
  • Import tariffs on South African steel entering the Eurozone
  • The loss of AGOA benefits in September
  • Ongoing uncertainty around the new Mining Charter

Geopolitical tensions and the Middle East conflict continue to disrupt global markets and limit trade, as reflected in data released since the conflict began.

A silver lining

There is some good news, however. Certain mining materials essential to steelmaking remain temporarily exempt from the higher US tariffs. This exemption offers welcome relief to a sector that remains vital to South Africa’s economy, providing jobs, earning foreign exchange and supporting overall growth.


More Coverage

South Africa’s August 2026 inflation data present a complex outlook: headline CPI rose to 4.4%, remaining below market expectations yet above the upper limit of the inflation target range, while services inflation continued to climb, and fuel and transport costs exerted further pressure on households and businesses. With the economy contracting, international oil prices rising and global uncertainties, including Middle East tensions and tariff disputes, continuing to weigh on the rand and domestic prices, attention is now focused on the South African Reserve Bank’s next interest-rate decision. Read the full report for an analysis of the factors driving inflation, the risks facing the economy and what the latest developments could mean for consumers, businesses and monetary policy in the months ahead.
The recent Electoral Court ruling dismissing the ANC’s bid to compel the IEC to accept late candidate submissions is a significant event with profound implications for the upcoming 4 November 2026 local government elections.
South Africa’s retail sector delivered a striking surprise in July 2026, with sales climbing 3.4% against market expectations of a 3.0% contraction, but the story beneath that headline number is far more nuanced than it first appears. This report unpacks the fragile balancing act facing local households: inflation easing to 4.3% yet still stubbornly above the SARB’s new 2–4% target band, administered prices and utility costs rising by more than 4.0%, wage growth lagging behind severe fuel shocks, and the lingering effect of May’s 25-basis-point rate hike prompted by inflationary pressures well beyond Pretoria’s control. We examine why business confidence firmed (SACCI up from 123.5 to 125.4) while consumer sentiment slumped sharply (FNB/BER down from -7 to -19), which categories, from “other retailers” to general dealers and household goods, actually carried the growth, and what the extension of AGOA to end-2027 means now that fresh visa tensions between Washington and Pretoria have placed South Africa’s eligibility squarely under the microscope. Read the full report to understand whether this recovery has the legs to survive higher fuel prices, a possible second rate increase, and a second-quarter contraction in economic activity — or whether July’s good news was simply borrowed from the easing cycle of 2024/25.
South Africa’s business profitability showed surprising resilience in the second quarter of 2026, outpacing inflation despite a 0.2% contraction in economic activity, higher oil and import prices, trade tariffs, and ongoing diplomatic tensions. While overall profit growth slowed from the first quarter, several sectors, including transport and logistics, mining, electricity and utilities, personal services, and trade, recorded substantial gains, offering important clues about where the economy’s strongest opportunities may lie. This report examines the forces shaping Gross Operating Surplus across key industries, explains the mounting pressures on company performance, and considers whether easing geopolitical tensions, lower oil prices, and greater policy certainty could unlock stronger economic activity, employment, and investment in the months and years ahead.
South Africa’s international liquidity position strengthened in August 2026, with net gold and foreign exchange reserves rising by USD 1,9 billion as the rand gained nearly 30c against the US dollar and the gold price climbed to USD 4 460/oz, some 30% higher than a year earlier. Yet beneath these encouraging headline figures lies a far more complex picture: the ongoing conflict in the Middle East and tensions around the Strait of Hormuz are keeping oil prices elevated, while shifting US tariff measures, a one-year AGOA extension and the Federal Reserve’s decision to hold rates steady all point to continued volatility for the rand. With the South African Reserve Bank’s third-quarter interest rate decisions hanging in the balance, this report unpacks what these commodity and currency movements mean for inflation, the mining sector and South Africa’s economic outlook for the remainder of the year.