Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is an authorised Financial Services Provider (FSP 46449) under the Financial Advisory and Intermediary Services Act (37 of 2002)
September 2, 2026

Why Hiking Interest Rates on Imported Inflation Will Stifle South Africa’s Fragile Economy

South Africa’s latest inflation figures provide some welcome relief, but a renewed surge in global oil prices threatens to undermine this progress. With fuel prices rising sharply due to external geopolitical and supply-side pressures, the debate over whether the SARB should respond with higher interest rates has become increasingly important. This article argues that raising rates to combat imported inflation would risk doing more harm than good—placing further pressure on households, businesses and investment in an economy already facing weak growth, high unemployment and significant industrial challenges.

At first glance, South Africa’s latest inflation statistics offered a collective sigh of relief. The Producer Price Index (PPI) slowed to 5.7% year-on-year in July 2026, down notably from 7.5% in June. Similarly, headline consumer inflation (CPI) cooled from 5.0% in June to 4.3% in July, edging closer to the South African Reserve Bank’s (SARB) newly lowered target band of 2% to 4%.

However, this statistical reprieve is already being overshadowed by global geopolitical shocks. With renewed conflict in the Middle East and severe disruptions to maritime transit through the Strait of Hormuz, international crude oil prices have surged. Despite a resilient Rand holding near R16.10/$ against the US dollar, the Department of Mineral and Petroleum Resources gazetted aggressive fuel price hikes, effective 2 September 2026: +R1.34 per liter for petrol and over R2.90 to R3.15 per liter for diesel.

As the Monetary Policy Committee (MPC) prepares to convene on 23 September 2026, speculation is mounting that the SARB may hike the repo rate to defend its target range. Yet raising domestic interest rates in response to supply-side, imported energy shocks would be a serious policy misstep, one that risks choking an already struggling real economy.

The Imported Fuel Shock: A R56 Billion Blow

South Africa ranks among the hardest-hit nations globally by the current energy crisis, having paid an estimated extra R56.3 billion for imported fuel since the onset of the Middle East conflict.

  • The Supply Chain Mechanism: Because diesel powers freight rail alternatives, agricultural machinery, and long-haul food transport, a R3/litre diesel jump cascades through the entire value chain.
  • Cost-Push Pressures: Higher transportation costs affect nearly every price in the economy, eroding consumer purchasing power and compressing corporate margins.
  • Calls for Fiscal Relief: This heavy multiplier effect has prompted public sector unions to demand urgent petrol price tax relief to ease the burden on workers. Raising interest rates does not pump a single extra barrel of oil or reopen maritime shipping lanes; it merely penalizes domestic businesses and households already bearing an external energy tax.

A Fragile Real Economy Under Severe Pressure

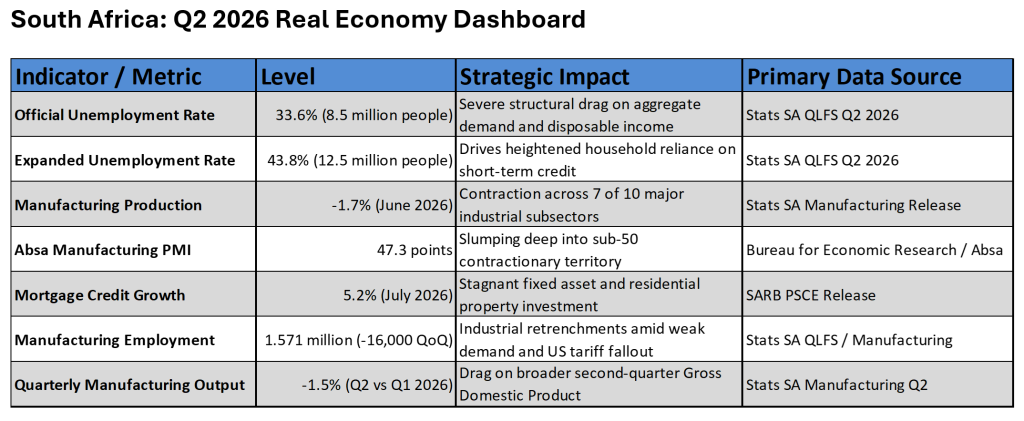
A tightening monetary stance overlooks the severe distress inside the productive domestic economy:

  • Crippling Unemployment: The official jobless rate climbed to 33.6% in Q2 2026 (expanded unemployment sits at 43.8%), with over 8.5 million South Africans locked out of work.
  • Industrial Contraction: Manufacturing output contracted 1.7% in June, while the Purchasing Managers’ Index (PMI) slumped to 47.3 points, deep in contractionary territory.
  • Factory Closures: Key industrial pillars, such as the automotive components sector, face factory closures and retrenchments amid high production costs, low vehicle sales, cheap foreign imports and restricted access to the US market.

Tepid Domestic Credit Demand: Private sector credit extension (PSCE) growth remains subdued. High borrowing costs and cost-of-living pressures have stymied mortgage advances (5.2%), while Gross Fixed Capital Formation (GFCF) remains depressed as businesses hesitate to fund expansion projects.
Trade Friction and the Need for Market Realism

Compounding domestic challenges are heightened trade headwinds. Following trade friction with Washington, South African exports to the United States have fallen roughly 56%. While the African Growth and Opportunity Act (AGOA) has been extended, South Africa’s eligibility remains subject to ongoing discretionary review.

At the same time, trade experts warn that South Africa is dropping the ball in trade negotiations with key partners such as China, India, Japan, and the Middle East, failing to secure the reciprocal market access needed for value-added goods. Protecting and expanding trade agreements is critical to restoring manufacturing and agricultural employment.

The Policy Verdict: Hold the Line on Rates

The South African Reserve Bank’s primary mandate is price stability, but monetary policy must distinguish between demand-driven overheating and supply-side external shocks.

South Africa’s current inflationary impulse is imported, driven by global conflict and petroleum logistics. Squeezing domestic demand with higher interest rates will not lower international oil prices. Instead, it will drive up the cost of capital, suppress fixed investment (GFCF), and accelerate corporate insolvencies in labour-heavy manufacturing and mining.

The sensible path for the MPC on 23 September is to look through the transitory fuel spike, hold interest rates steady, and allow structural economic reforms and trade diplomacy to support the recovery.


More Coverage

South Africa’s August 2026 inflation data present a complex outlook: headline CPI rose to 4.4%, remaining below market expectations yet above the upper limit of the inflation target range, while services inflation continued to climb, and fuel and transport costs exerted further pressure on households and businesses. With the economy contracting, international oil prices rising and global uncertainties, including Middle East tensions and tariff disputes, continuing to weigh on the rand and domestic prices, attention is now focused on the South African Reserve Bank’s next interest-rate decision. Read the full report for an analysis of the factors driving inflation, the risks facing the economy and what the latest developments could mean for consumers, businesses and monetary policy in the months ahead.
The recent Electoral Court ruling dismissing the ANC’s bid to compel the IEC to accept late candidate submissions is a significant event with profound implications for the upcoming 4 November 2026 local government elections.
South Africa’s retail sector delivered a striking surprise in July 2026, with sales climbing 3.4% against market expectations of a 3.0% contraction, but the story beneath that headline number is far more nuanced than it first appears. This report unpacks the fragile balancing act facing local households: inflation easing to 4.3% yet still stubbornly above the SARB’s new 2–4% target band, administered prices and utility costs rising by more than 4.0%, wage growth lagging behind severe fuel shocks, and the lingering effect of May’s 25-basis-point rate hike prompted by inflationary pressures well beyond Pretoria’s control. We examine why business confidence firmed (SACCI up from 123.5 to 125.4) while consumer sentiment slumped sharply (FNB/BER down from -7 to -19), which categories, from “other retailers” to general dealers and household goods, actually carried the growth, and what the extension of AGOA to end-2027 means now that fresh visa tensions between Washington and Pretoria have placed South Africa’s eligibility squarely under the microscope. Read the full report to understand whether this recovery has the legs to survive higher fuel prices, a possible second rate increase, and a second-quarter contraction in economic activity — or whether July’s good news was simply borrowed from the easing cycle of 2024/25.
South Africa’s business profitability showed surprising resilience in the second quarter of 2026, outpacing inflation despite a 0.2% contraction in economic activity, higher oil and import prices, trade tariffs, and ongoing diplomatic tensions. While overall profit growth slowed from the first quarter, several sectors, including transport and logistics, mining, electricity and utilities, personal services, and trade, recorded substantial gains, offering important clues about where the economy’s strongest opportunities may lie. This report examines the forces shaping Gross Operating Surplus across key industries, explains the mounting pressures on company performance, and considers whether easing geopolitical tensions, lower oil prices, and greater policy certainty could unlock stronger economic activity, employment, and investment in the months and years ahead.
South Africa’s international liquidity position strengthened in August 2026, with net gold and foreign exchange reserves rising by USD 1,9 billion as the rand gained nearly 30c against the US dollar and the gold price climbed to USD 4 460/oz, some 30% higher than a year earlier. Yet beneath these encouraging headline figures lies a far more complex picture: the ongoing conflict in the Middle East and tensions around the Strait of Hormuz are keeping oil prices elevated, while shifting US tariff measures, a one-year AGOA extension and the Federal Reserve’s decision to hold rates steady all point to continued volatility for the rand. With the South African Reserve Bank’s third-quarter interest rate decisions hanging in the balance, this report unpacks what these commodity and currency movements mean for inflation, the mining sector and South Africa’s economic outlook for the remainder of the year.