Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is an authorised Financial Services Provider (FSP 46449) under the Financial Advisory and Intermediary Services Act (37 of 2002)
July 17, 2026

Squeezing a Stone: Why the SARB’s Blunt-Force Rate Hike Threat Misses the Mark for Squeezed Consumers

With inflation largely driven by global supply-side pressures rather than strong consumer demand, another SARB interest rate hike may do little to reduce price increases while placing additional strain on already financially stretched South African households. Although higher rates may help anchor inflation expectations and support the Rand, they risk slowing economic growth, increasing loan defaults, and further weakening consumer spending.

The South African Reserve Bank (SARB) is facing an intense debate as its Monetary Policy Committee (MPC) prepares for its next interest rate decision on 23 July 2026.

With the Rand showing signs of vulnerability at R16.45/$, Producer Price Inflation (PPI) climbing to 7.8%, and Consumer Price Inflation (CPI) ticking up to 4.5%, market expectations are heavily leaning toward another 25-basis-point hike to the repo rate, which currently sits at 7.00% (10.50% Prime).

Yet, for news-oriented and investment-driven market participants, the burning question is not whether they will do it, but rather: Is this the right economic medicine, or are we simply trying to squeeze blood from a stone?

The Blunt Instrument vs. The Structural Sickness

The fundamental critique of further monetary tightening in South Africa lies in the nature of our current inflation. Interest rate hikes are designed to combat demand-pull inflation, when an economy is growing too quickly, and excess cash is chasing too few goods.

However, South Africa is suffering from a textbook case of cost-push inflation, driven by factors entirely outside the SARB’s sphere of influence:

  • Geopolitical Oil Spikes: The recent escalation in the Middle East has kept Brent Crude highly volatile. No amount of domestic rate hikes can alter OPEC supply policies or secure shipping corridors.
  • Factory-Gate Pressures: The 7.8% PPI print shows that input costs are rising long before goods reach retail shelves. Squeezing consumer liquidity does not lower the cost of raw materials or industrial chemicals on global markets.
  • The Diesel Under-Recovery Threat: While temporary petrol over-recoveries offered a brief respite, massive daily under-recoveries in diesel (~R1.90/l) signal that structural transport and logistics costs are set to remain elevated, adding a persistent tax on local business operations.

A Middle Class Running on Empty

Draining further liquidity from the domestic system is highly problematic given the health of the average South African consumer.

The latest TransUnion Q2 2026 Consumer Pulse Study paints a stark picture of the domestic credit climate:
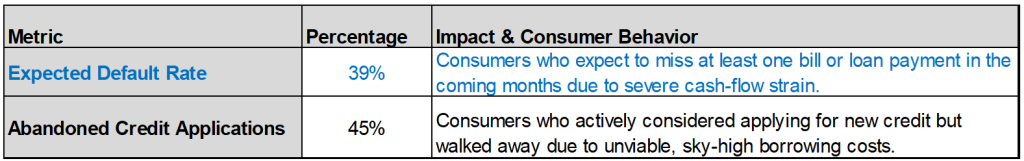
These metrics tell us that the domestic savings buffer has been completely decimated. Draining more liquidity from households that are already running on empty will not stop them from driving to work or buying food. It will simply increase the rate of non-performing loans, erode banking book quality, and severely stall South Africa’s fragile GDP growth trajectory.

The Governor’s Dilemma: Controlling the Uncontrollable

If a rate hike is so economically destructive to the local consumer, why is Governor Lesetja Kganyago still widely expected to pull the trigger? The answer lies in the narrow, rigid mandate of inflation targeting.
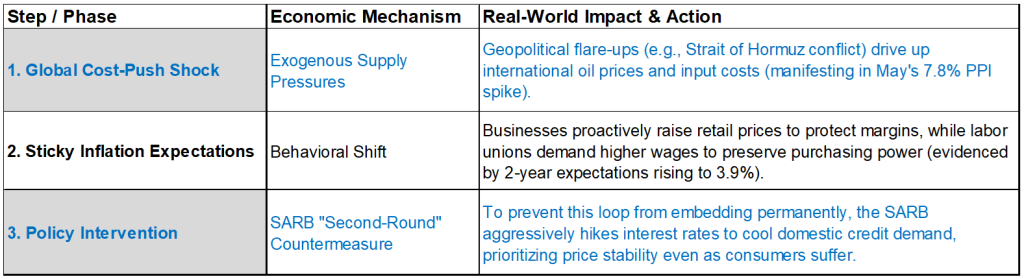
The SARB Hikes Rates to “Break” this Expectation Loop

While the SARB knows it cannot print oil, it is deeply concerned about second-round inflation expectations. According to the latest Bureau for Economic Research (BER) survey, two-year-ahead inflation expectations have risen to 3.9%.

If local businesses and labour unions begin pricing in a permanent 4% to 5% inflation baseline, high prices will become structurally embedded in the economy. By raising rates, the central bank is effectively trying to shock local “price-setters” into keeping their prices low, even if it means triggering a domestic slowdown.

Ultimately, while the SARB’s hawkishness aims to protect the Rand and anchor long-term expectations, it is a blunt tool for a delicate job. Squeezing a dry consumer is a high-risk policy path that will test the resilience of South African investments in the second half of 2026.


More Coverage

South Africa’s August 2026 inflation data present a complex outlook: headline CPI rose to 4.4%, remaining below market expectations yet above the upper limit of the inflation target range, while services inflation continued to climb, and fuel and transport costs exerted further pressure on households and businesses. With the economy contracting, international oil prices rising and global uncertainties, including Middle East tensions and tariff disputes, continuing to weigh on the rand and domestic prices, attention is now focused on the South African Reserve Bank’s next interest-rate decision. Read the full report for an analysis of the factors driving inflation, the risks facing the economy and what the latest developments could mean for consumers, businesses and monetary policy in the months ahead.
The recent Electoral Court ruling dismissing the ANC’s bid to compel the IEC to accept late candidate submissions is a significant event with profound implications for the upcoming 4 November 2026 local government elections.
South Africa’s retail sector delivered a striking surprise in July 2026, with sales climbing 3.4% against market expectations of a 3.0% contraction, but the story beneath that headline number is far more nuanced than it first appears. This report unpacks the fragile balancing act facing local households: inflation easing to 4.3% yet still stubbornly above the SARB’s new 2–4% target band, administered prices and utility costs rising by more than 4.0%, wage growth lagging behind severe fuel shocks, and the lingering effect of May’s 25-basis-point rate hike prompted by inflationary pressures well beyond Pretoria’s control. We examine why business confidence firmed (SACCI up from 123.5 to 125.4) while consumer sentiment slumped sharply (FNB/BER down from -7 to -19), which categories, from “other retailers” to general dealers and household goods, actually carried the growth, and what the extension of AGOA to end-2027 means now that fresh visa tensions between Washington and Pretoria have placed South Africa’s eligibility squarely under the microscope. Read the full report to understand whether this recovery has the legs to survive higher fuel prices, a possible second rate increase, and a second-quarter contraction in economic activity — or whether July’s good news was simply borrowed from the easing cycle of 2024/25.
South Africa’s business profitability showed surprising resilience in the second quarter of 2026, outpacing inflation despite a 0.2% contraction in economic activity, higher oil and import prices, trade tariffs, and ongoing diplomatic tensions. While overall profit growth slowed from the first quarter, several sectors, including transport and logistics, mining, electricity and utilities, personal services, and trade, recorded substantial gains, offering important clues about where the economy’s strongest opportunities may lie. This report examines the forces shaping Gross Operating Surplus across key industries, explains the mounting pressures on company performance, and considers whether easing geopolitical tensions, lower oil prices, and greater policy certainty could unlock stronger economic activity, employment, and investment in the months and years ahead.
South Africa’s international liquidity position strengthened in August 2026, with net gold and foreign exchange reserves rising by USD 1,9 billion as the rand gained nearly 30c against the US dollar and the gold price climbed to USD 4 460/oz, some 30% higher than a year earlier. Yet beneath these encouraging headline figures lies a far more complex picture: the ongoing conflict in the Middle East and tensions around the Strait of Hormuz are keeping oil prices elevated, while shifting US tariff measures, a one-year AGOA extension and the Federal Reserve’s decision to hold rates steady all point to continued volatility for the rand. With the South African Reserve Bank’s third-quarter interest rate decisions hanging in the balance, this report unpacks what these commodity and currency movements mean for inflation, the mining sector and South Africa’s economic outlook for the remainder of the year.