Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
July 1, 2026

South Africa’s Inflation Dilemma: Why Bleeding an Anaemic Patient Won’t Cure the Illness

In “South Africa’s Inflation Dilemma: Why Bleeding an Anaemic Patient Won’t Cure the Illness,” the article navigates the precarious economic landscape facing South Africa amidst rising inflation and stagnant growth. With consumer demand faltering due to slow wage growth, recent fuel price hikes, and increased municipal fees, the country stands at a critical junction. The looming threat of another interest rate hike by the South African Reserve Bank could further cripple an already fragile economy, likened to an anaemic patient, with potential long-term repercussions for job creation and corporate investment. However, recent geopolitical developments offer a flicker of hope, as a ceasefire in the US-Iran conflict has led to a decline in global oil prices, promising immediate relief for consumers and a slower inflation trajectory. The article argues that maintaining the current repo rate is essential to allow this relief to translate into economic growth and stability. Dive into the full report to explore how South Africa can navigate these turbulent waters without sacrificing its fragile economic health.

The South African economy is currently walking a high-stakes macroeconomic tightrope. Domestically, consumer demand remains incredibly fragile, with local households squeezed from multiple angles: slow wage growth, recent spikes in fuel costs, and a 25-basis-point interest rate hike in May. Compounding this pain, skyrocketing municipal “administered” prices, including water and electricity hikes of up to 9% across major metros, kick in today.

With economic growth barely clinging to a 1% trajectory, our economy desperately needs liquidity to foster expansion and job creation.

Yet, external forces have heavily clouded the monetary policy landscape. A global energy crisis linked to the US-Iran conflict recently drove producer-side costs through the roof, pushing South Africa’s Producer Price Inflation (PPI) to a worrying 7.8% for May. Because PPI serves as an early warning indicator of general consumer inflation, global institutions such as Goldman Sachs and Oxford Economics have predicted that the South African Reserve Bank (SARB) will raise interest rates again at its upcoming July 23 meeting. Currently, forward-rate agreements (FRAs) indicate an 88% probability of a quarter-point increase, aimed at preventing two-year inflation expectations (which recently ticked up to 3.9%) from becoming entrenched.

This brings us to a critical crossroad for domestic policy. Increasing the repo rate beyond its current 7.00% to combat imported inflationary pressures risks doing severe, long-term damage to our local market.

Draining vital liquidity from an economy growing at just 1% is akin to bleeding a sick patient. When a patient is already profoundly anaemic, forcing further blood loss will not cure an external infection; it will simply cause the patient to collapse. For South Africa, another rate hike will not lower global oil prices or fix geopolitical conflicts; it will simply crush any remaining consumer confidence, freeze corporate capital expenditure, and kill off near-term employment growth.

Fortunately, the economic landscape has shifted dramatically over the last few weeks. A recent ceasefire between the US and Iran has allowed global Brent Crude to retreat to roughly $86.53 per barrel, while the Rand has held steady at an average of R16.38 to the US Dollar.

The immediate result of this geopolitical cooling hits South African pumps today: a massive supply-side relief of R2.00 per litre for petrol and R3.60 per litre for diesel. This relief will fundamentally alter the inflation trajectory in two distinct phases:

  • In the Short-Term: Headline CPI will receive an instant cooling effect, pulling it safely away from the upper boundary and providing immediate cash-flow relief to commuters.
  • In the Medium-Term: The R3.60/L drop in diesel significantly lowers input costs for agriculture and the road-freight logistics sector, which moves 80% of the country’s goods. This drop acts as a natural brake on the 7.8% PPI pressure, slowing down the second-round food and retail inflation spikes that the central bank fears most.
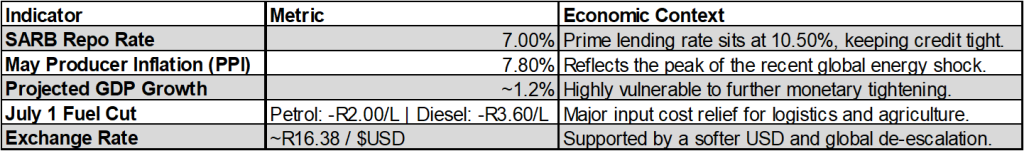
While central bank policymakers are notoriously conservative, they are also strictly data dependent. Because the recent inflation scare was purely imported rather than driven by an overheating domestic market, the dramatic drop in energy costs gives the Monetary Policy Committee (MPC) a strong, data-backed justification to pause and maintain the repo rate at 7.00% on July 23.

Holding the rate steady will allow this massive fuel price relief to filter through the system naturally. It avoids an unnecessary, destructive liquidity drain and gives our anaemic domestic economy the vital breathing room it needs to heal, invest, and grow.


More Coverage

South Africa’s August 2026 inflation data present a complex outlook: headline CPI rose to 4.4%, remaining below market expectations yet above the upper limit of the inflation target range, while services inflation continued to climb, and fuel and transport costs exerted further pressure on households and businesses. With the economy contracting, international oil prices rising and global uncertainties, including Middle East tensions and tariff disputes, continuing to weigh on the rand and domestic prices, attention is now focused on the South African Reserve Bank’s next interest-rate decision. Read the full report for an analysis of the factors driving inflation, the risks facing the economy and what the latest developments could mean for consumers, businesses and monetary policy in the months ahead.
The recent Electoral Court ruling dismissing the ANC’s bid to compel the IEC to accept late candidate submissions is a significant event with profound implications for the upcoming 4 November 2026 local government elections.
South Africa’s retail sector delivered a striking surprise in July 2026, with sales climbing 3.4% against market expectations of a 3.0% contraction, but the story beneath that headline number is far more nuanced than it first appears. This report unpacks the fragile balancing act facing local households: inflation easing to 4.3% yet still stubbornly above the SARB’s new 2–4% target band, administered prices and utility costs rising by more than 4.0%, wage growth lagging behind severe fuel shocks, and the lingering effect of May’s 25-basis-point rate hike prompted by inflationary pressures well beyond Pretoria’s control. We examine why business confidence firmed (SACCI up from 123.5 to 125.4) while consumer sentiment slumped sharply (FNB/BER down from -7 to -19), which categories, from “other retailers” to general dealers and household goods, actually carried the growth, and what the extension of AGOA to end-2027 means now that fresh visa tensions between Washington and Pretoria have placed South Africa’s eligibility squarely under the microscope. Read the full report to understand whether this recovery has the legs to survive higher fuel prices, a possible second rate increase, and a second-quarter contraction in economic activity — or whether July’s good news was simply borrowed from the easing cycle of 2024/25.
South Africa’s business profitability showed surprising resilience in the second quarter of 2026, outpacing inflation despite a 0.2% contraction in economic activity, higher oil and import prices, trade tariffs, and ongoing diplomatic tensions. While overall profit growth slowed from the first quarter, several sectors, including transport and logistics, mining, electricity and utilities, personal services, and trade, recorded substantial gains, offering important clues about where the economy’s strongest opportunities may lie. This report examines the forces shaping Gross Operating Surplus across key industries, explains the mounting pressures on company performance, and considers whether easing geopolitical tensions, lower oil prices, and greater policy certainty could unlock stronger economic activity, employment, and investment in the months and years ahead.
South Africa’s international liquidity position strengthened in August 2026, with net gold and foreign exchange reserves rising by USD 1,9 billion as the rand gained nearly 30c against the US dollar and the gold price climbed to USD 4 460/oz, some 30% higher than a year earlier. Yet beneath these encouraging headline figures lies a far more complex picture: the ongoing conflict in the Middle East and tensions around the Strait of Hormuz are keeping oil prices elevated, while shifting US tariff measures, a one-year AGOA extension and the Federal Reserve’s decision to hold rates steady all point to continued volatility for the rand. With the South African Reserve Bank’s third-quarter interest rate decisions hanging in the balance, this report unpacks what these commodity and currency movements mean for inflation, the mining sector and South Africa’s economic outlook for the remainder of the year.