Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
August 14, 2025

A View on Demand in the Economy

Retail Sales Performance

June 2025
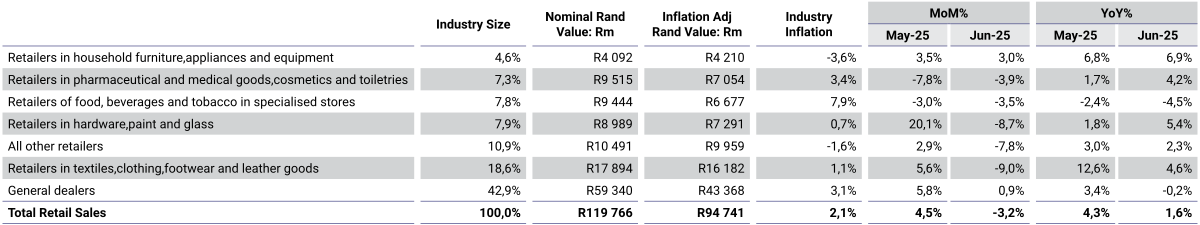
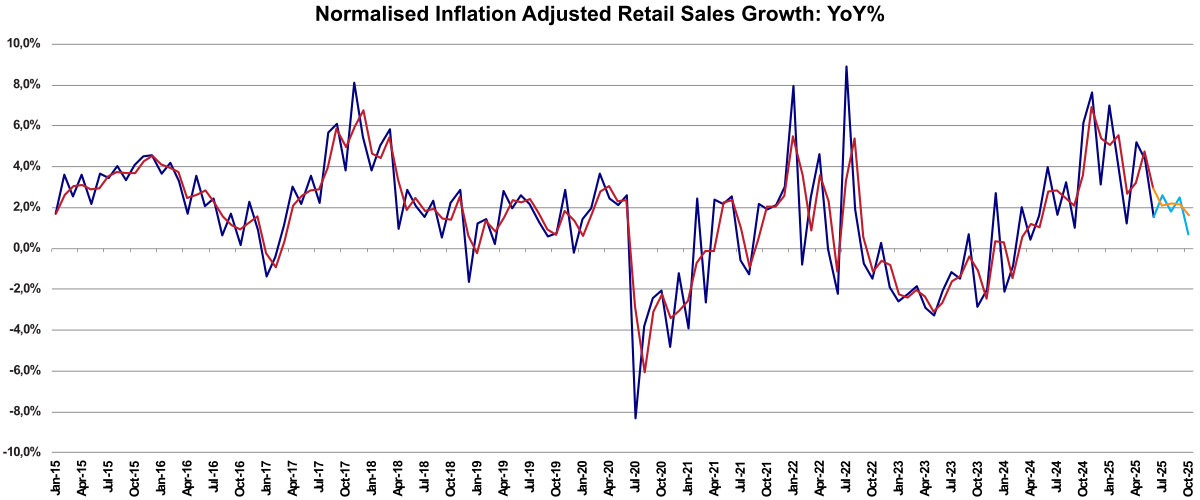
Retail sales in South Africa grew by 1.6% in June, falling notably short of the market expectations of 3.0% as forecasted by analysts for the month. This modest growth suggests that consumer demand in the South African economy is beginning to slow, reflecting a cautious approach to spending amid ongoing economic pressures.

This slowdown comes as no surprise, given the challenges households face, including rising living costs, stagnant wages due to sluggish economic growth, and uncertainties surrounding South Africa’s international trade relations with the US. Diplomatic tensions between Washington and Pretoria and the failure to reach a new trade agreement with one of South Africa’s key trading partners have also contributed to this cautious environment.

The 1.6% increase in June indicates a slow but steady rebound in consumer demand, likely supported by interest rate cuts and monetary easing introduced since September 2024.

The South African Chamber of Commerce and Industry (SACCI) reported a decline in business confidence, with its index dropping from 115.8 in May to 113.2 in June 2025. Meanwhile, the FNB/BER consumer index for the second quarter of 2025 improved from -20 to -10 points, signalling cautious but positive shifts in consumer sentiment from a banking perspective. Despite low inflation and the Reserve Bank’s interest rate reductions in January and July 2025, these factors are gradually influencing consumer behaviour and spending patterns.

Key contributors to the modest rise in retail sales included:

  • Hardware, paint and glass: up 5.4%, contributing 0.4 percentage points.
  • Textiles and clothing: increased by 4.6%, adding 0.8 percentage points.

This modest growth in June reflects continued positive momentum from May’s retail performance and indicates a fragile but manageable recovery in consumer demand. The interest rate cuts between September 2024 and July 2025 have alleviated household financial pressures, supporting a gradual uptick in demand over the past three months. Maintaining this momentum will be vital throughout 2025, as consumer spending remains a key driver of economic growth and employment in South Africa. Further interest rate reductions later in the year could also help sustain demand into late 2025 and early 2026.


More Coverage

For South African businesses and households already managing a tight financial squeeze, the South African Reserve Bank’s (SARB) recent decision to hike the repo rate to 7.0% felt less like economic medicine and more like a handbrake. While central banks traditionally raise interest rates to cool down an overheating economy, South Africa’s current reality is vastly different. Our recent inflation spike isn’t driven by a wild shopping spree, but by global supply shocks and an imported energy crisis. This begs the crucial question: is the SARB using the wrong tool for the job, and at what cost to our fragile economic growth?
The case for holding interest rates is strong, as South Africa’s current inflation is being driven by global supply-side pressures like fuel prices, not excessive local spending. Raising rates now would place additional strain on already struggling consumers and businesses without addressing the real cause of inflation. With the Rand strengthening, oil prices stabilising, and diesel costs expected to decline, natural inflation relief is already emerging. Since inflation remains within the SARB’s target range, increasing borrowing costs could unnecessarily slow economic growth and job creation.
Amid a turbulent economic backdrop, South Africa’s retail sales surged by an unexpected 2.6% in March 2026, outpacing forecasts and signalling a fragile yet persistent recovery in the consumer market. While interest rate cuts have bolstered household spending, challenges such as rising inflation, potential interest rate hikes, and geopolitical tensions loom large. Despite these hurdles, sectors like “other retailers” and general dealers have notably contributed to this growth spurt, raising questions about the sustainability of this recovery. With business and consumer confidence indices displaying mixed signals, the future of South Africa’s retail strength hinges on international relations, fuel costs, and policy decisions. Explore the dynamics and implications of these developments in our detailed report.
In an insightful analysis of South Africa’s economic landscape in April 2026, the report delves into the notable 4.0% year-on-year increase in the Consumer Price Index, accentuated by surging costs in housing, utilities, transport, and financial services. Amid rising inflationary pressures fuelled by global uncertainties, including the Middle East conflict and climbing oil prices, the South African Reserve Bank faces critical decisions on interest rates to balance inflation and economic growth. As households grapple with diminished purchasing power, the precarity of reliance on short-term credit looms large, while international factors such as US-imposed tariffs and potential BRICS trade tensions threaten market stability. The report provides a comprehensive look at the delicate dance South Africa must perform to maintain price stability and safeguard the Rand amidst a challenging global backdrop.
Next week’s SARB decision could define South Africa’s economic trajectory: facing an external oil shock and runaway electricity tariffs that threaten to push April inflation past the central bank’s 4.0% ceiling, policymakers must weigh a technical inflation breach against a staggering surge in unemployment and collapsing investment, a choice between credibility and survival. With joblessness spiking and GDP growth stagnant, aggressive rate hikes would risk choking off the private investment the country urgently needs, while inaction could dent the new inflation-targeting framework. Read the full report for a detailed breakdown of the shocks driving this dilemma, the likely “hold” outcome from the May 28 MPC meeting, and what it means for businesses, households, and markets.